SUMMARY
Having said that, continued investments in exploration and development of discoveries and fields will be needed to offset the anticipated decline in production.
"It's truly inspiring that successful exploration can still be achieved on such a mature shelf," says Torgeir Stordal, Director General of the Norwegian Offshore Directorate.
Last year was the second-best exploration year in ten years –surpassed only by 2021. Many discoveries were made, some of which were significant. Several discoveries are the result of applying advanced new technology. Among other things, more than ten kilometres of wellbores have been drilled.
Summarising the year on the shelf
"The Shelf in 2025" is a summary of activity on the Norwegian continental shelf over the past year: Exploration and production results, as well as investment and production forecasts for the next five years.
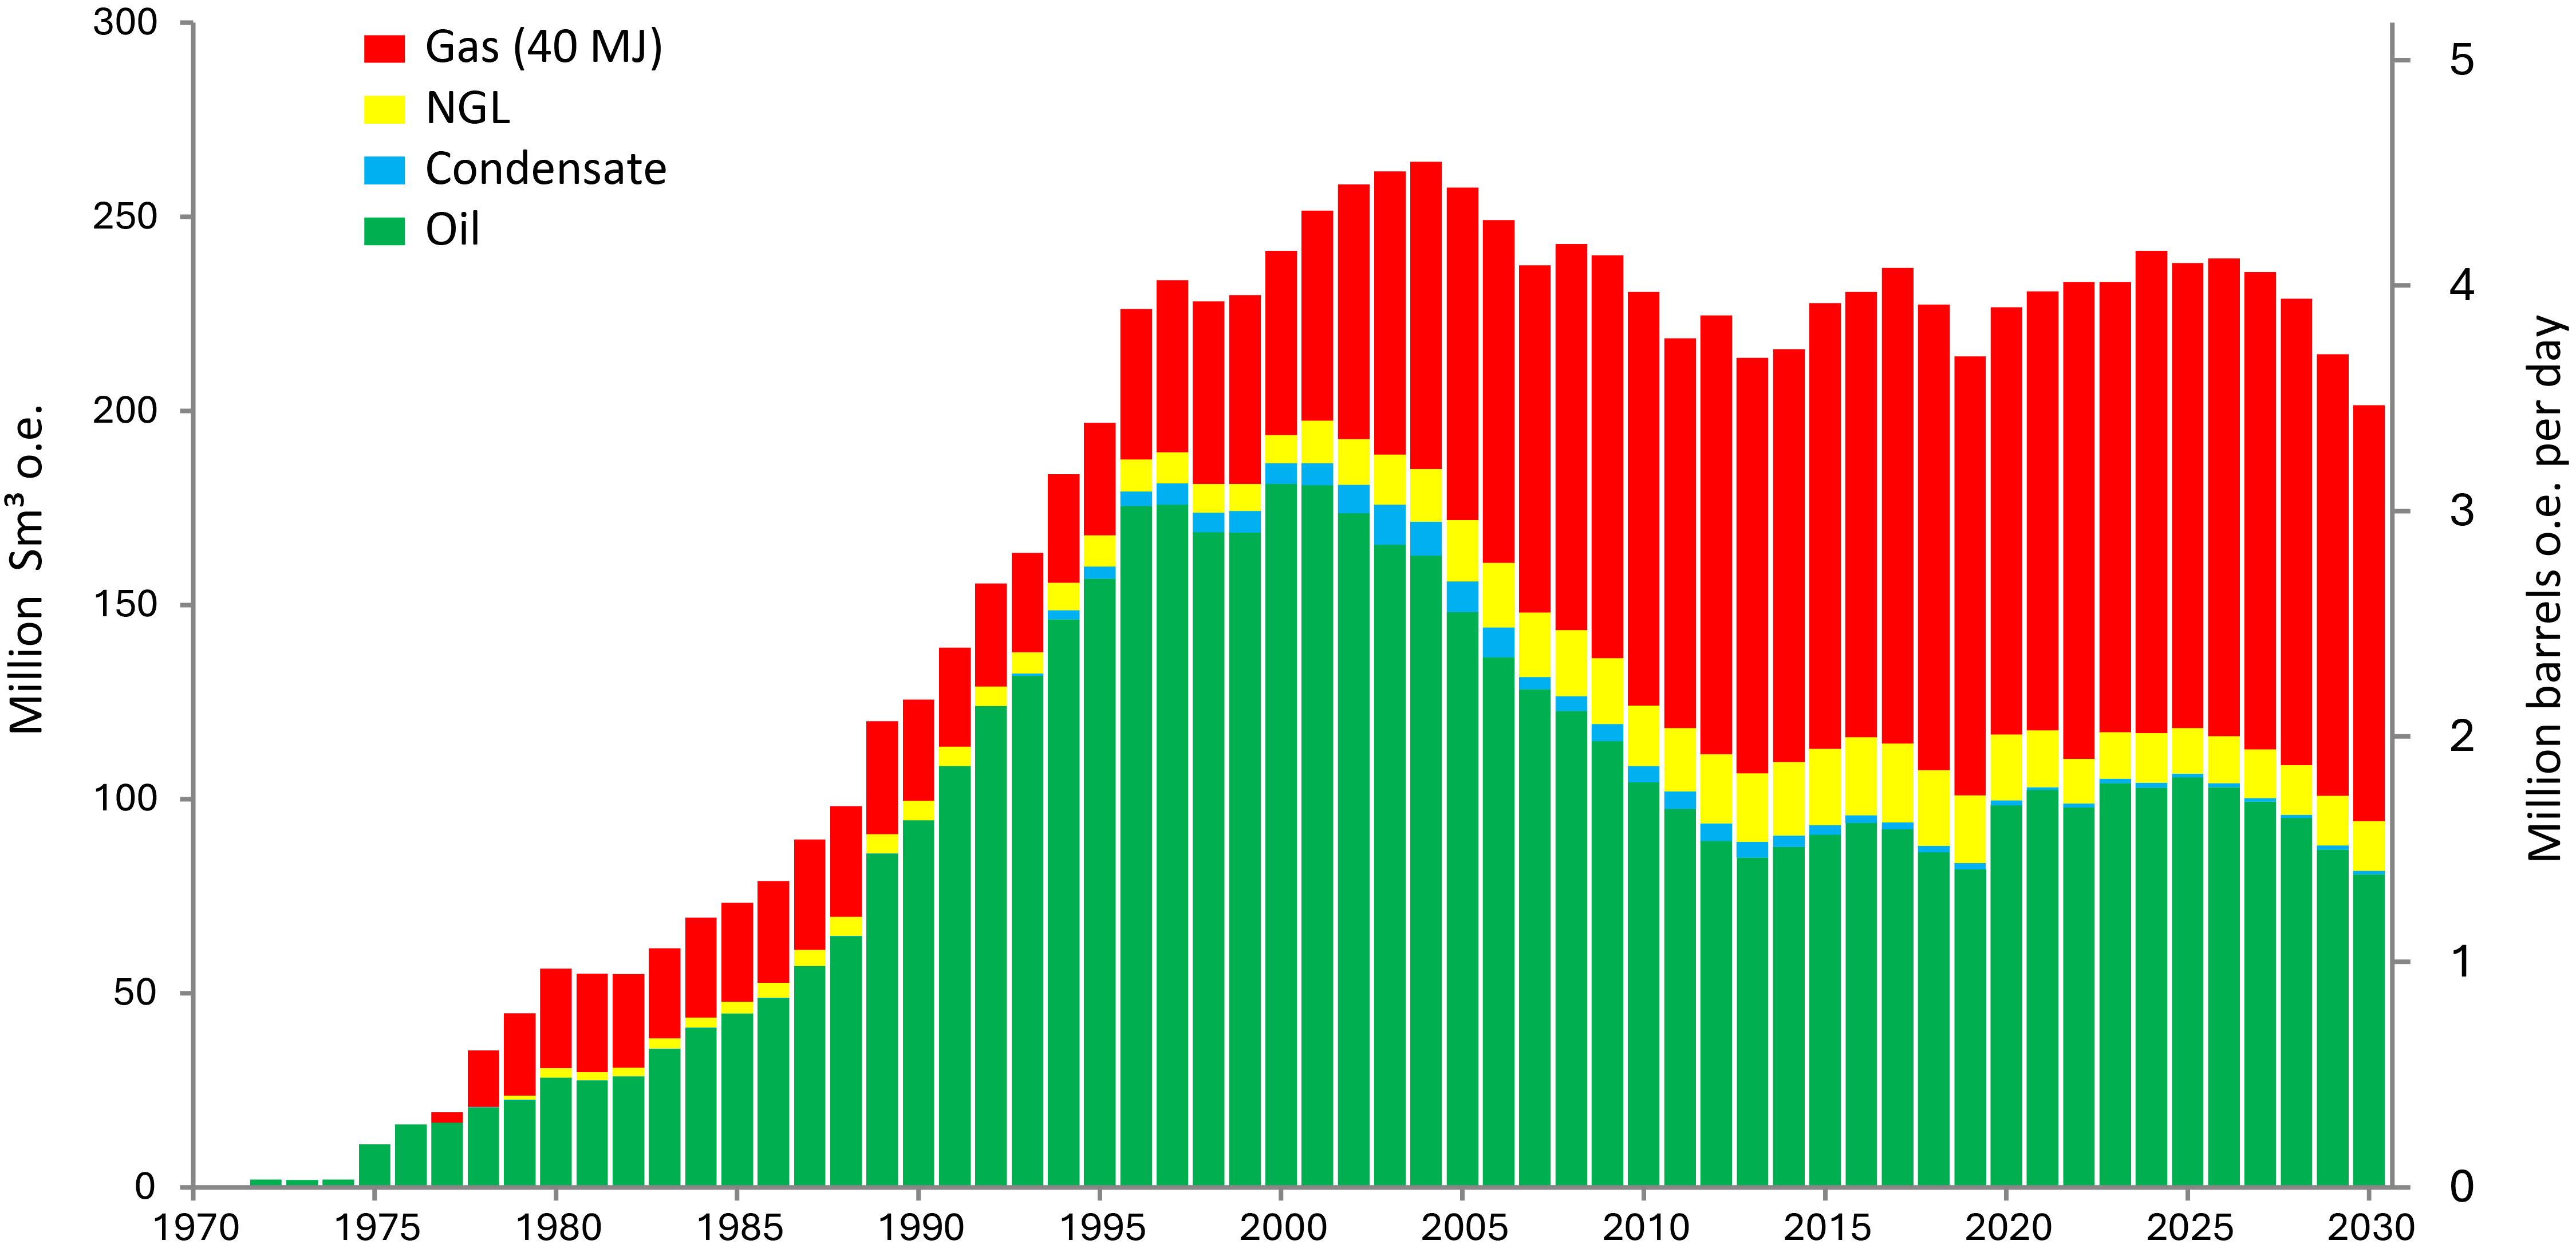
Both production and investments were very high in 2025. Oil production (106 million standard cubic metres is the highest since 2009. Production from the NCS is nearly equally distributed between oil and gas. A total of 120 billion standard cubic metres was sold, which represents a minor reduction from the record-breaking year of 2024.
"We expect gas production to remain at this level over the next three to four years. Norwegian gas accounts for about 30 per cent of EU gas consumption, and Norway is Europe's largest supplier after cutting off Russian gas," Stordal says.
Exploration and investments are needed
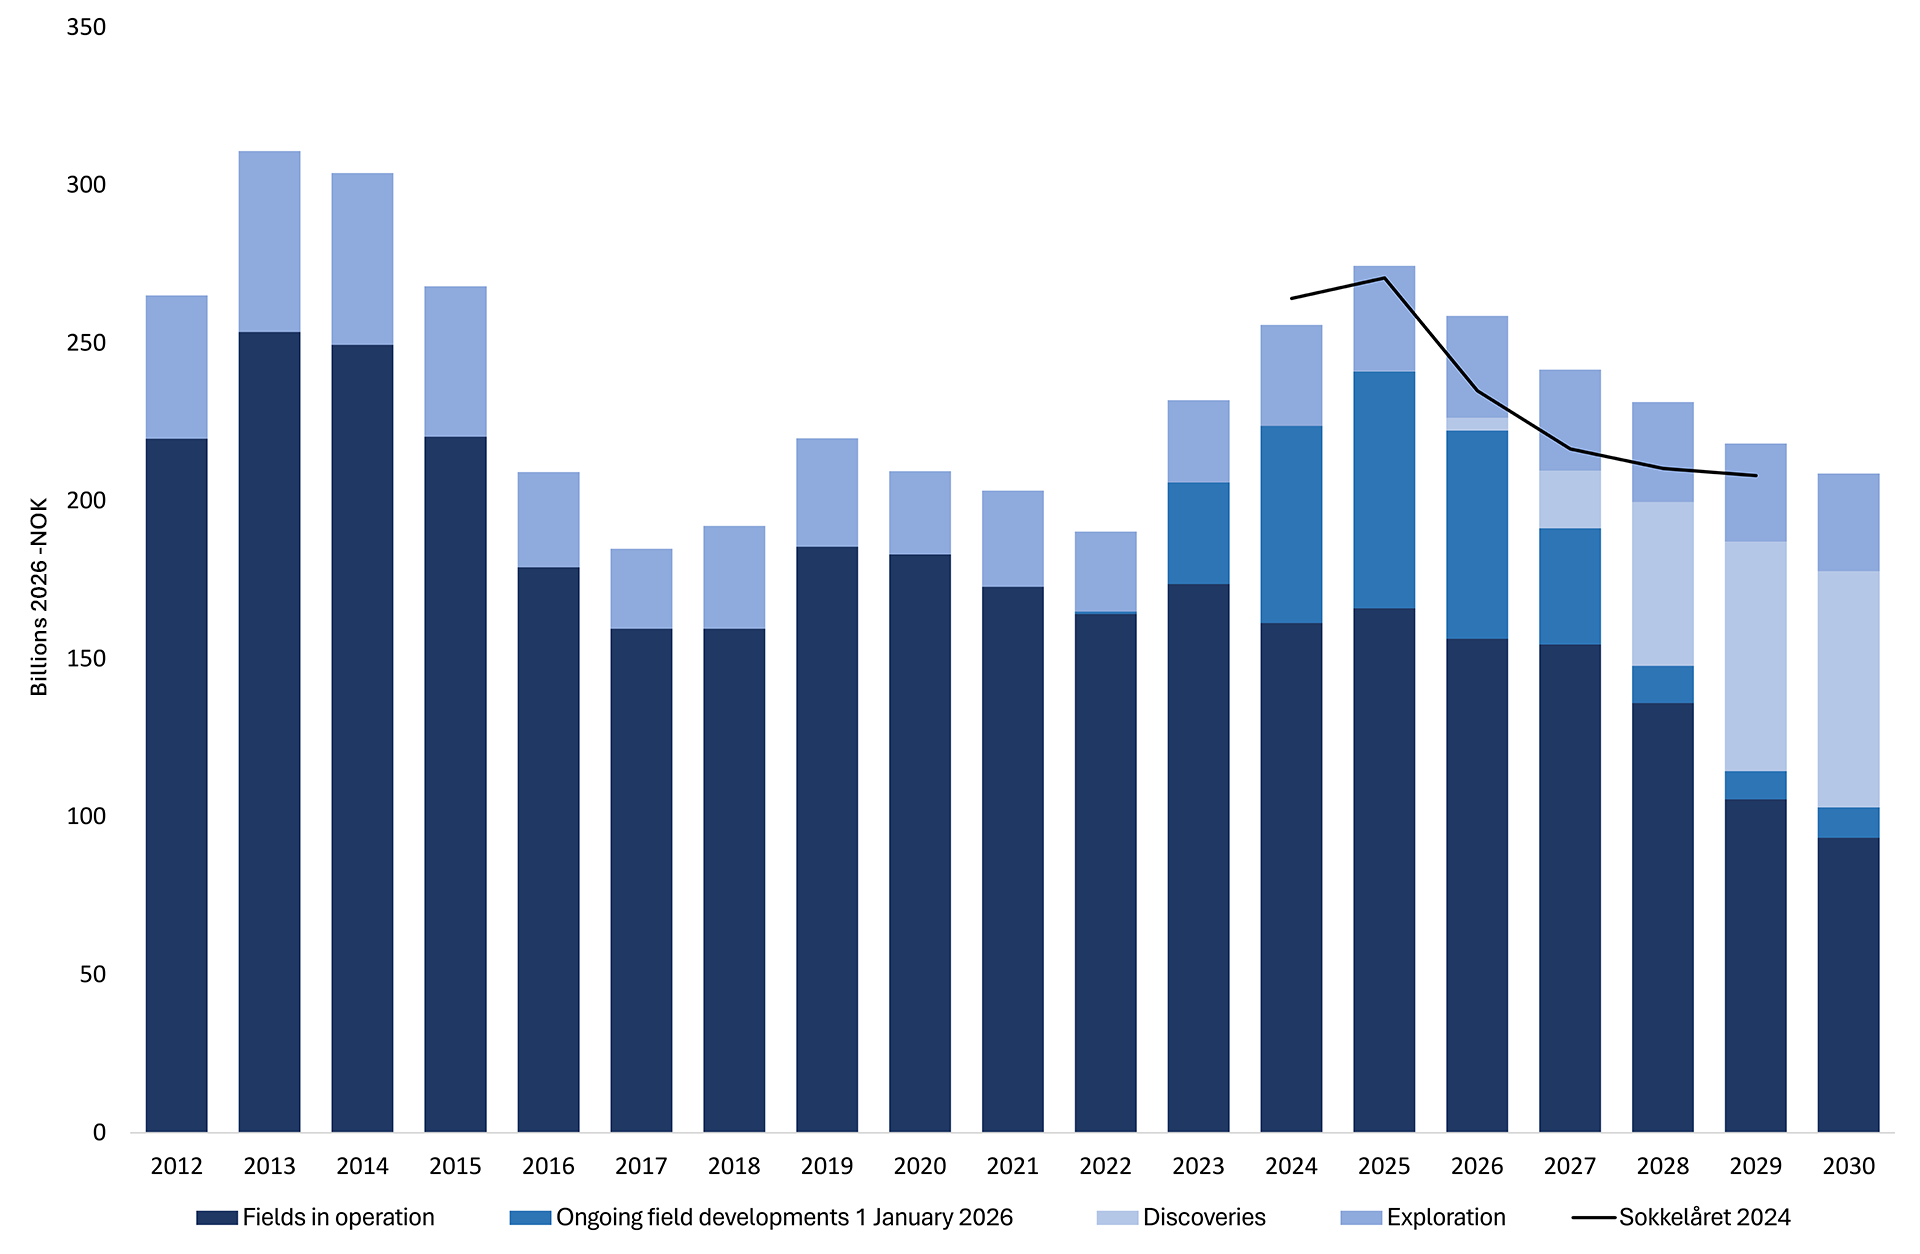
In 2026, the Norwegian Offshore Directorate expects investments of NOK 256 billion, a reduction of 6,5 per cent from last year. Leading up to 2030, we expect the investment level to decline gradually due to the completion of development projects without equivalent new projects to replace them.
Toward the end of the 2020s, the Directorate expects a reduction in overall production. A number of new field development decisions will be needed in order to slow this anticipated decline. It will also be important to maintain high exploration activity. Failing to invest will lead to a substantial dismantling of the petroleum industry.
There is significant interest in secure storage of CO2 on the NCS. 2025 saw the establishment of the world’s first full-scale value chain for carbon capture and storage. The Norwegian Offshore Directorate also mapped mineral resources and environmental conditions in the relevant areas.
Production, operating Fields and investments
Read about:
- Oil production up, gas down slightly
- High level of investment, but a decline is expected
- Awards in pre-defined areas (APA)
- Projects and developments
- Production start-up and continuation
- Emissions and power from shore
Oil production up, gas down slightly
Oil production in 2025 amounted to about 106 million standard cubic metres (Sm3), which represents the highest level of production since 2009.
The Johan Sverdrup field in the North Sea accounts for close to 40 per cent of this, and the field has produced at plateau over the last three years. The field will continue to provide a significant share of oil production over the next few years, despite gradually declining from plateau.
The Johan Castberg field in the Barents Sea started producing in March and has gradually contributed to increased oil production on the shelf. The field reached plateau production in the summer of 2025, and the Directorate expects plateau production to be maintained for several years before a natural decline.
Production from the NCS is nearly equally distributed between oil and gas. A total of about 120 billion standard cubic metres of gas (Sm3) was sold. This is a minor reduction compared with the record-breaking year of 2024. We expect gas production to remain at this level over the next three to four years.
Norwegian gas accounts for about 30 per cent of EU gas consumption, and Norway is Europe's largest supplier after cutting off Russian gas.
The Troll field in the North Sea accounts for about one-third of overall gas production, and this situation will continue over the next few years.
Total production on the NCS (oil, gas, NGL and condensate) amounted to 238 million standard cubic metres of oil equivalent (MSm3 o.e.). Production is expected to remain at a stable, high level over the next few years, and will then gradually decline towards the end of the 2020s.
At year-end 2025, there were 97 fields in operation on the Norwegian shelf. The Halten Øst and Verdande fields in the Norwegian Sea, as well as Johan Castberg in the Barents Sea, came on stream, and no fields were shut down over the past year. The Norwegian Offshore Directorate expects a number of new fields to come on stream over the years to come.
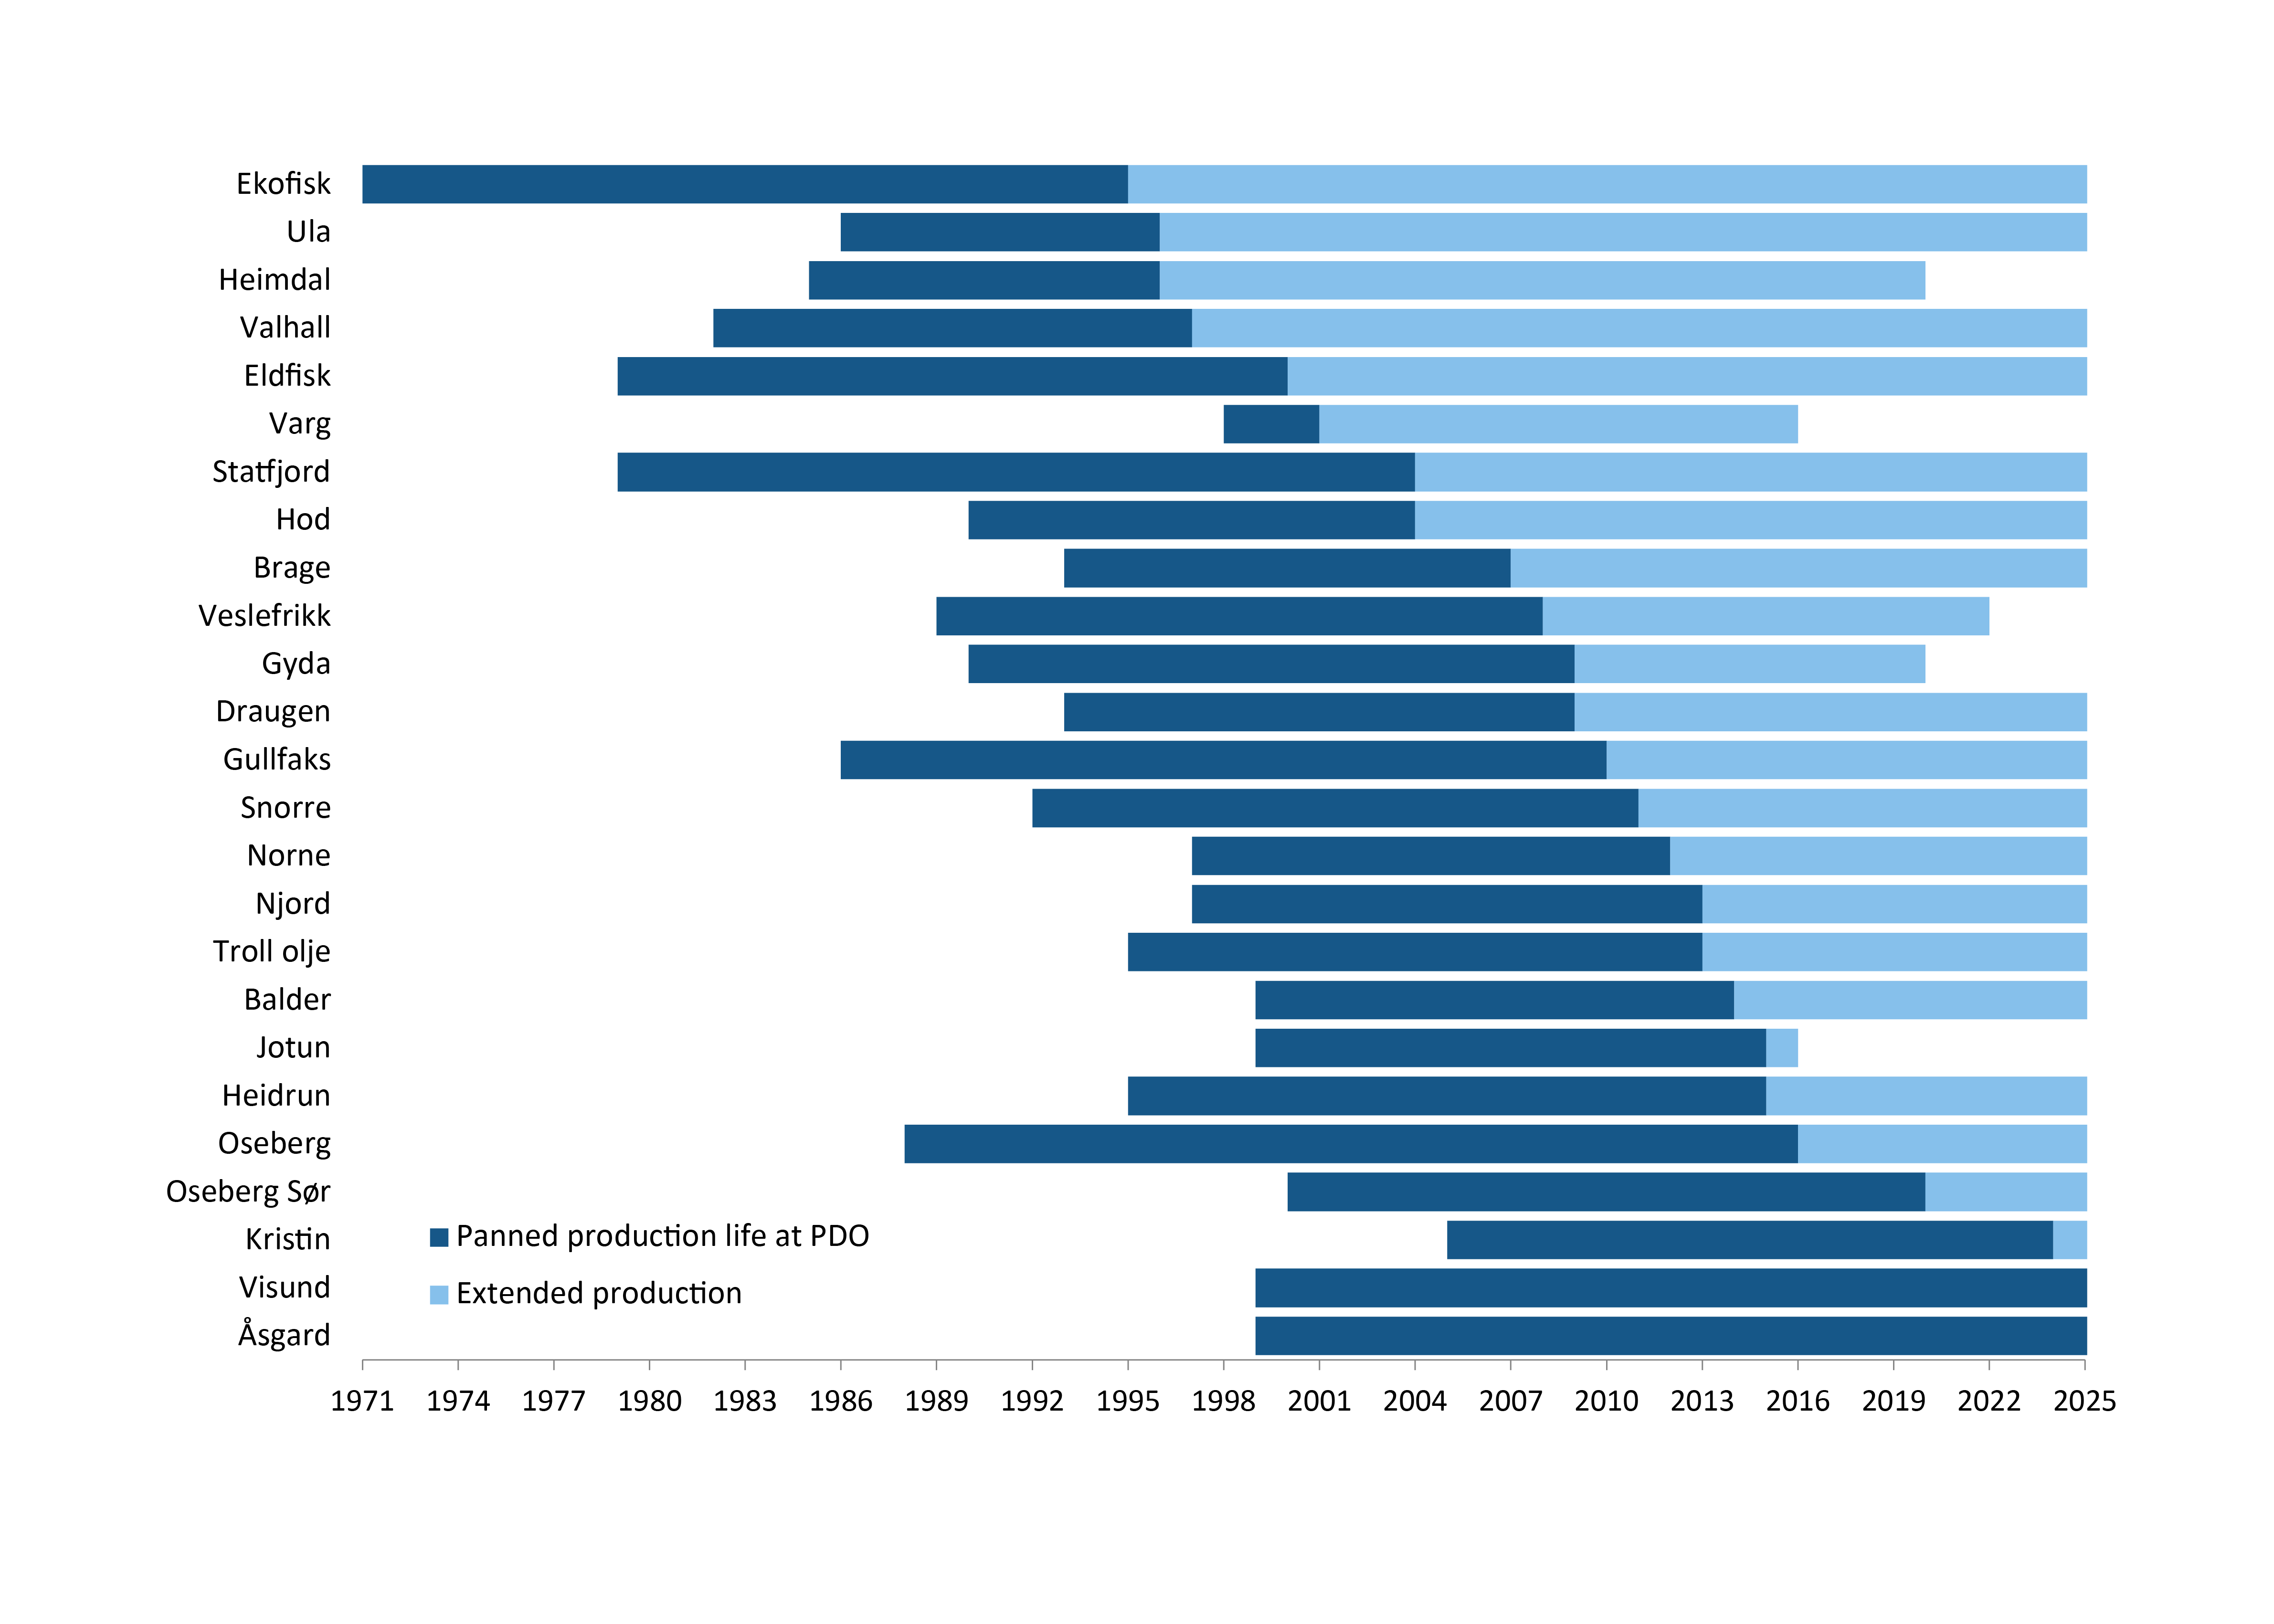
One important reason why production remains at such high levels is that the fields are producing for longer than originally planned. New and improved technology has allowed us to continuously improve our understanding of the subsurface. This has enabled the industry to further develop the fields. New development projects, more production wells and exploration in the surrounding area have helped extend the lifetimes of most fields.
Certain fields that are no longer producing are also being considered for reopening. They are planned with a simpler development solution tied back to existing and surrounding infrastructure. One example is the shuttered fields of Albuskjell, Vest Ekofisk and Tommeliten Gamma in the Greater Ekofisk Area. The plan for these fields is to develop them with a subsea solution tied back to the Ekofisk Complex.
The figure below shows a number of fields that are producing between 10 and 30 years longer than originally planned. Several of these fields will continue to produce after 2030, and some even to 2040. This will provide a significant contribution to production and value creation on the shelf.
The Norwegian Offshore Directorate publishes preliminary production figures on a monthly basis.
High level of investment, but a decline is expected
In 2026, the Norwegian Offshore Directorate expects investments on the NCS totalling NOK 256 billion. This represents a reduction of 6.5 per cent from the previous year. The Directorate expects the investment level to decline gradually leading up to 2030.
Significant activity and scarce capacity in parts of the supplier industry, presumed extended lifetimes for several production facilities and growth in costs have led to higher projected costs and investments. This is especially for 2026–2029, compared with what was presented in early 2025. Additional development wells and higher drilling costs per development well also contribute to a higher level of investment. Projected investments for certain ongoing developments have also increased (Prop. 1 S, 2025–2026) (Norwegian only).
The primary cause of falling investments moving forward is the gradual completion and production start-up of ongoing development projects. This will take place without new projects of an equivalent scope expected to come on stream.
A few previously planned projects aimed at reducing greenhouse gas emissions by transitioning to operations with power from shore have been suspended due to challenging profitability. These were investment-heavy projects that, according to earlier forecasts, accounted for a substantial share of the level of investment and activity leading up to 2030.
Despite the high level of activity in the industry in 2025, new investments will be necessary to maintain future production.
We expect exploration activity and exploration costs in 2026 to be somewhat lower than in 2025.
Awards in pre-defined areas (APA)
In January 2025, 20 companies were offered ownership interests in a total of 53 production licences in the awards in APA 2024.
When the application deadline for APA 2025 expired on 2 September, the authorities had received applications from 20 companies. This is on par with APA 2024 and shows that the Norwegian continental shelf remains attractive for exploration and long-term production. New production licences in the announced areas are expected to be awarded in early 2026.
The Norwegian Offshore Directorate has invited the companies to nominate blocks for the 26th licensing round on the NCS.
Projects and developments
Comprehensive area solutions are becoming increasingly important in connection with ongoing and future developments on the NCS. Crucial drivers include multiple minor discoveries, higher development costs, technical assessments of installation lifetimes and future emission profiles.
The plan for development and operation (PDO) for Fram Sør, which is located in the northern part of the North Sea, was approved in 2025. Investments in the project are estimated at about 21 billion 2025-NOK.
Several new development plans are expected over the upcoming years. Most of these are relatively small discoveries that are being developed with subsea templates or wells from existing subsea templates, and tied back to existing infrastructure.
At the end of the year (Proposition 1 S to the Storting (2025-2026) (Norwegian only), 17 development projects or field developments with approved development plans were under way on the NCS. Eight of the projects are in the North Sea, eight in the Norwegian Sea and one in the Barents Sea. These projects will help keep the investment level high and slow the underlying decline in production over the next decade. Additional development projects will also help extend lifetimes and thereby lead to improved recovery from existing fields.
The largest discoveries that have yet to be developed are 7324/8-1 (Wisting) in the Barents Sea, 6406/9-1 (Linnorm) in the Norwegian Sea and 35/2-1 (Peon) in the North Sea (see the chapter "Resources and challenges in discoveries" in Resource Report 2024). These discoveries are all being considered for development and could contribute considerable resources and values over the next few decades.
Production start-up and continuation
The consent system is how the authorities follow up to ensure that licensees conduct their activities in line with the regulations and previous decisions. The consent entails a verification that preconditions in the plan for development and operation (PDO), plan for installation and operation (PIO) and disposal decisions are fulfilled.
The table below shows consents for start up and continuation issued in 2025.
| Field/project | Consent to | Commencement/planned commencement |
| Askeladd Vest | Commencement of installations | 19 September 2025 |
| Ormen Lange phase 3 | Commencement and use of facilities | 26 August 2025 |
| Halten Øst | Commencement of installations | 17 March 2025 |
| Maria phase 2 | Commencements of new installations | 23 May 2025 |
| Smørbukk Midt | Commencement | 18 September 2025 |
| Troll B | Commencement and continuation of gas export solution | 12 October 2025 |
| Andvare | Commencement | 29 September 2025 |
| Verdande | Commencement | 25 November 2025 |
| Åsgard B low-pressure phase 3 | Commencement and continuation | Jan. 2026 |
| Kristin (installation) | Continuation | 23 October 2025 |
Emissions and power from shore
Despite relatively stable production, greenhouse gas emissions on the NCS have been declining since 2015. Converting to power from shore on the fields has been the most important measure.
Since 2015, these emissions have been reduced by 4.1 million tonnes, or 27 per cent. This is according to the report "Power from shore 2025", which the Norwegian Offshore Directorate prepared on assignment from the Ministry of Energy in 2025.
The primary source of emissions from the NCS is the combustion of gas in gas turbines. There are also emissions from the combustion of gas and diesel in boilers and motors, in safety flaring of ngas, diesel in turbines, engines and boilers, venting and fugitive gas emissions, as well as in connection with storage and loading of crude oil.
Emissions are expected to increase somewhat over the short term, followed by a new decline once ongoing projects to convert to power from shore are operational. Conversions to power from shore are under way on Melkøya, the Troll and Oseberg fields in the North Sea, as well as Njord and Draugen in the Norwegian Sea.
Recent years have brought several plans to convert to operations using power from shore. Many of these plans have been suspended due to the challenges faced to achieve profitability. Work is still under way to study power from shore to the Balder and Grane fields in the North Sea.
The distribution of emission sources from the petroleum sector
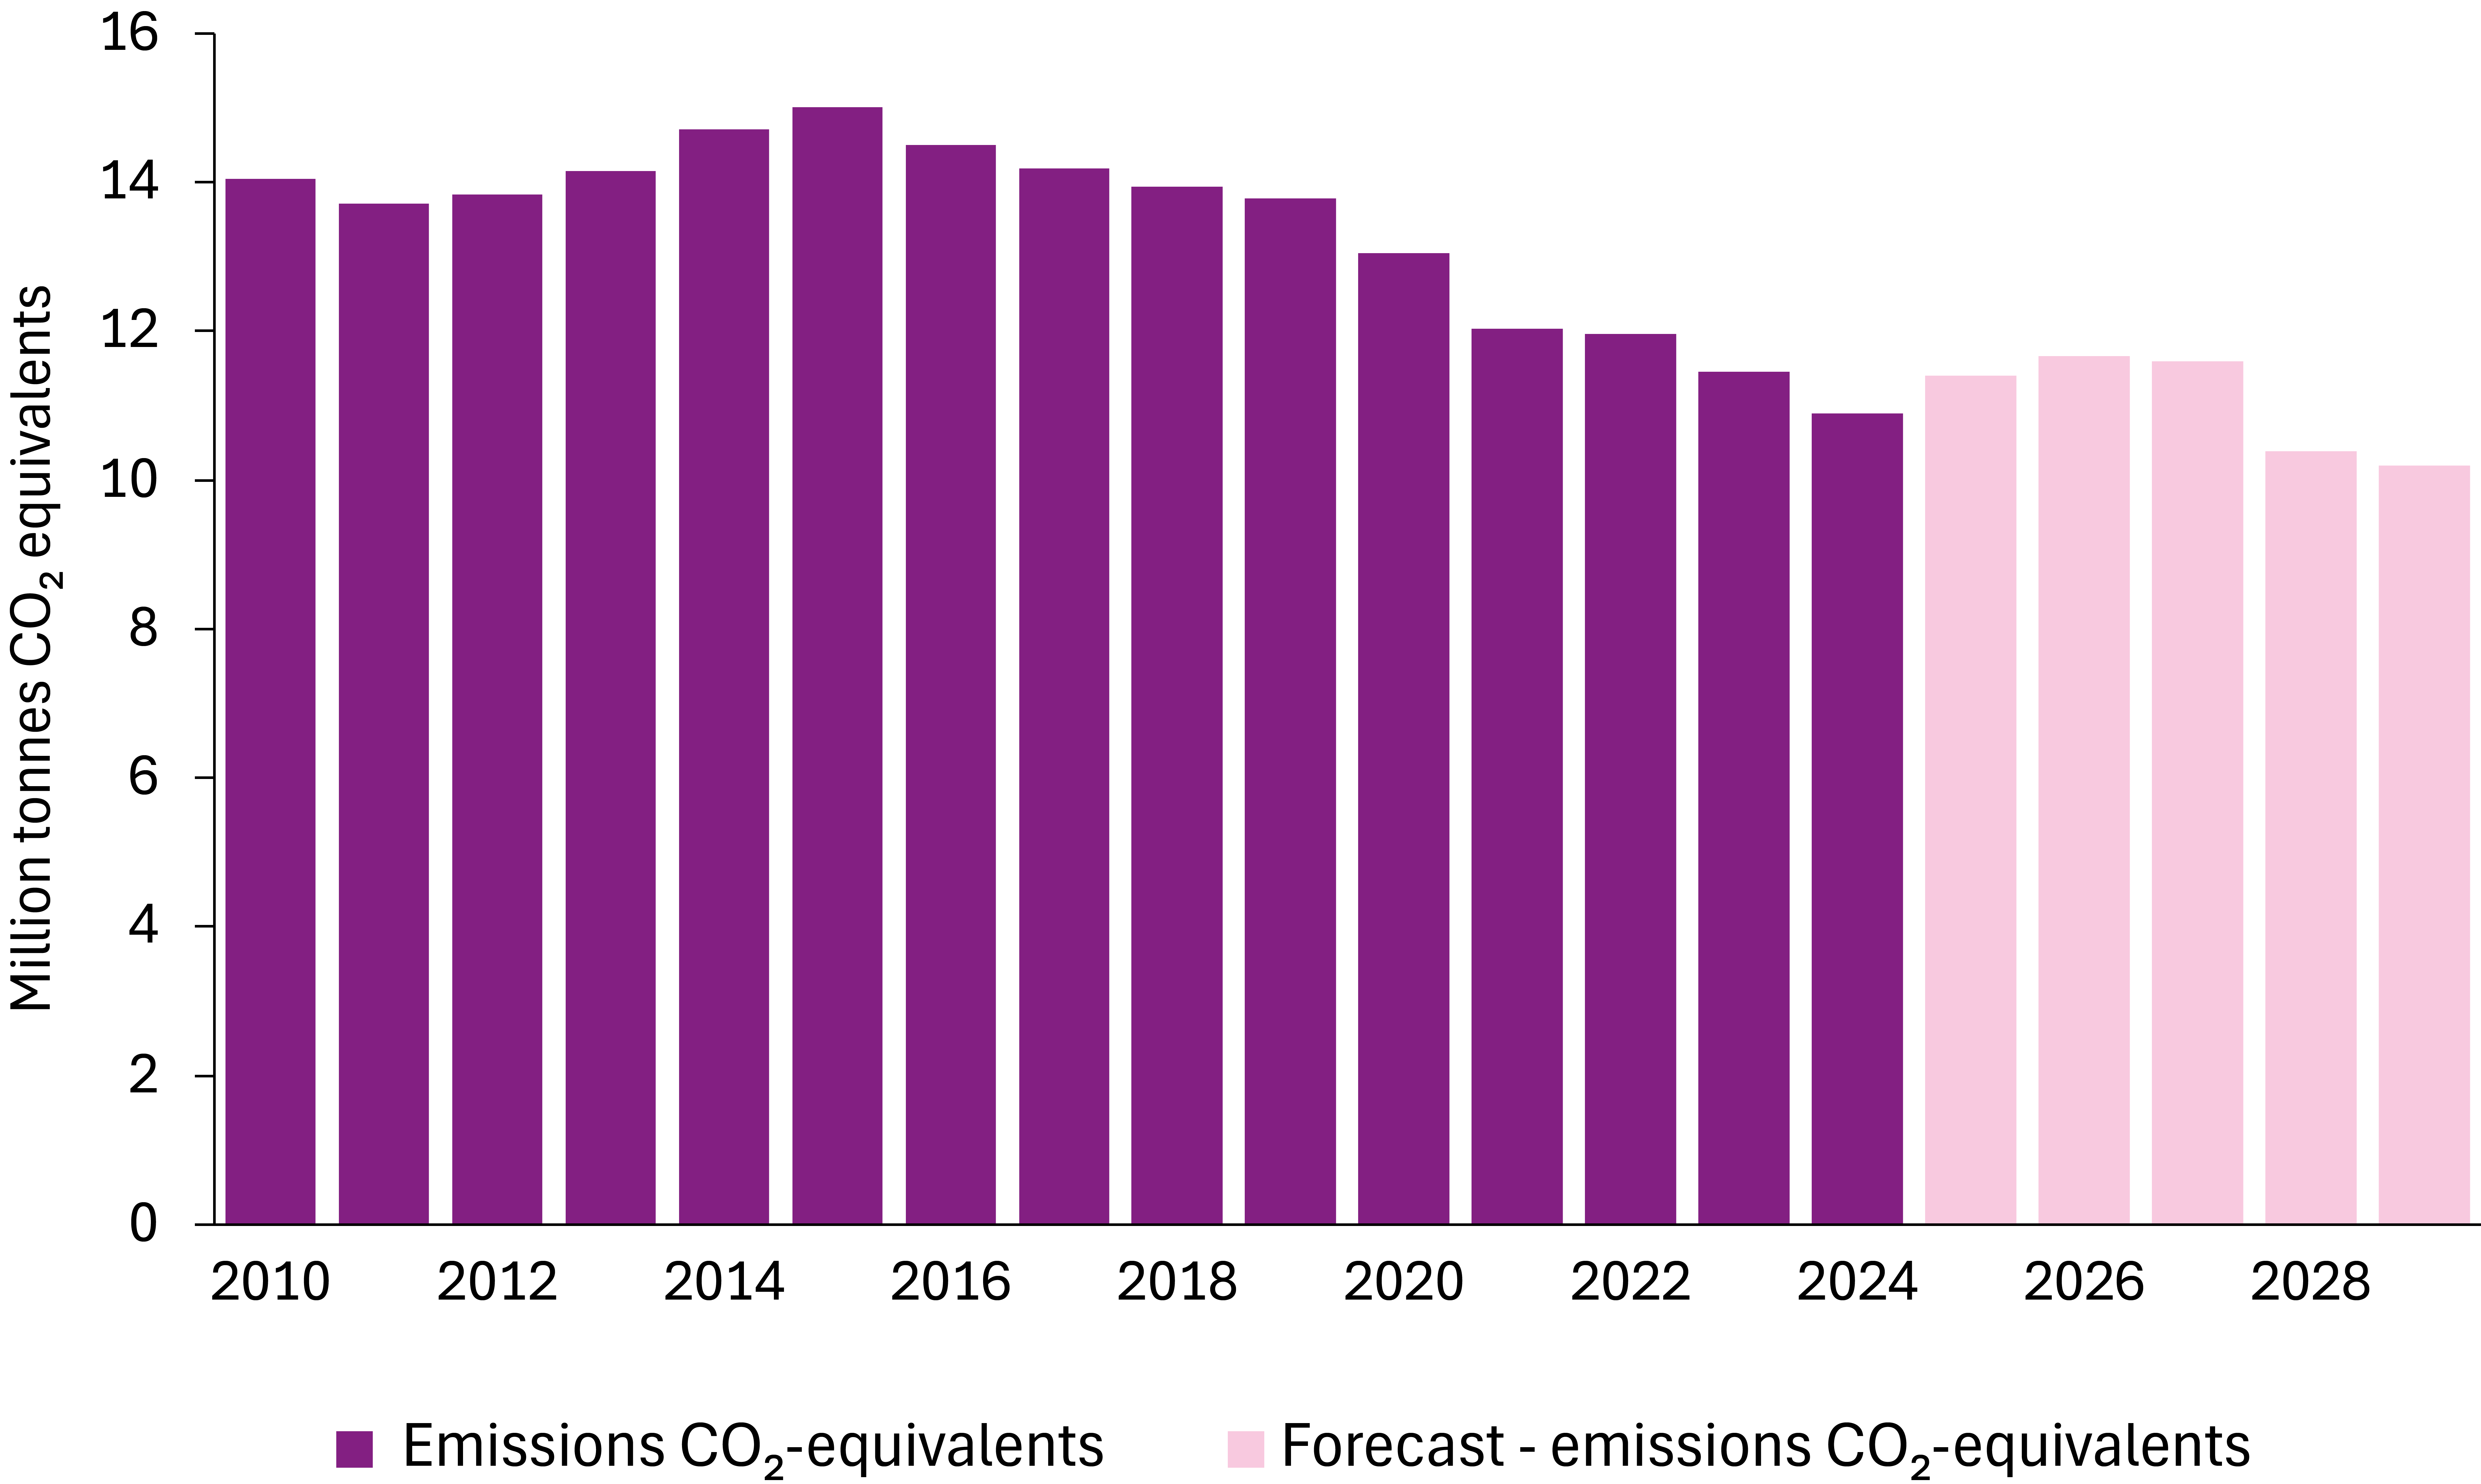
This figure is based on data from the National Budget for 2026. Power from shore projects that have been planned and which are now suspended, were not scheduled to be in operation until after 2033.
Download: Background data (Excel)
Oil and gas on the NCS moving forward
Read about:
What will it take to realise the resources?
In 2024, the Norwegian Offshore Directorate developed three potential scenarios for the overall production of oil and gas leading up to 2050. These were updated and presented at Sokkelkonferansen in 2025.
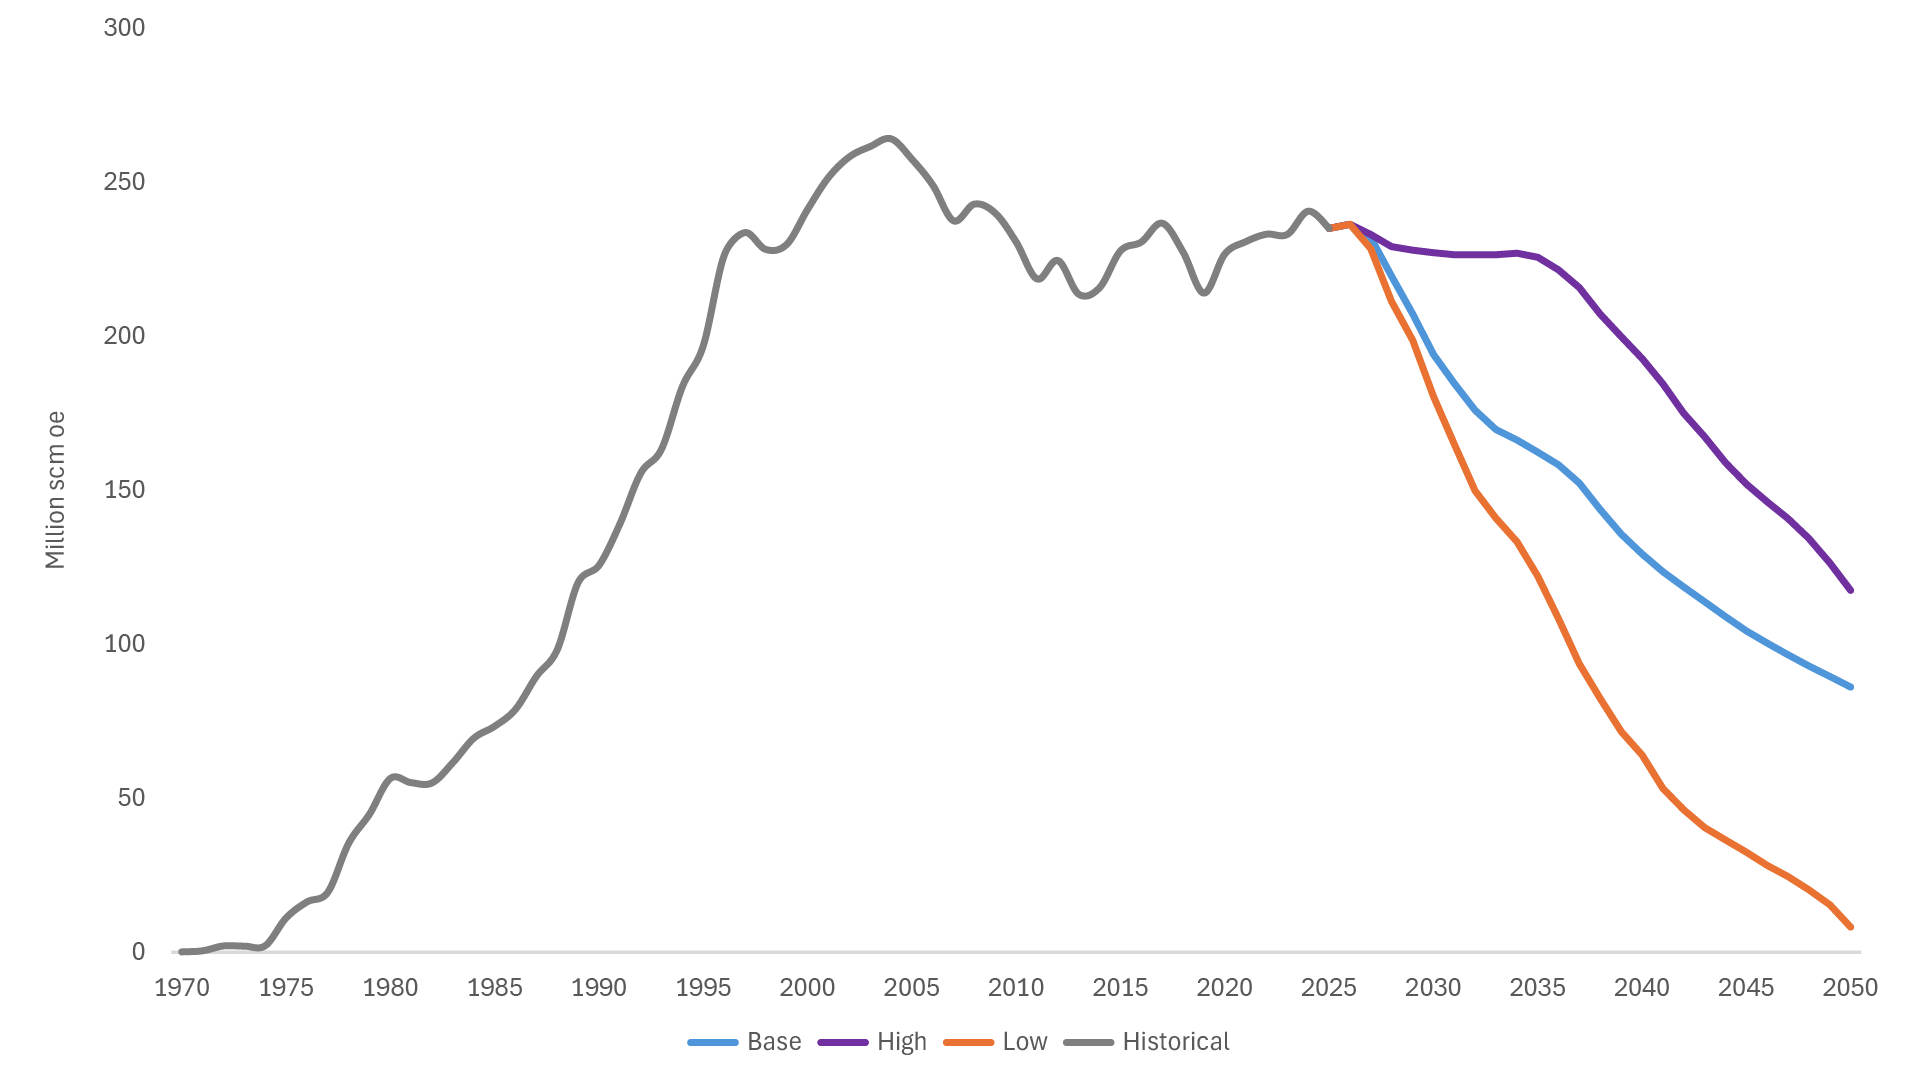
All three potential scenarios reflect declining production in the years to come. In order to slow this decline, exploration will need to take place close to infrastructure and in more frontier areas, in addition to making more investments in fields, discoveries and infrastructure. Failure to invest will lead to rapid dismantling of the petroleum activities.
There are still substantial resources in place on the NCS, but more exploration and more work will be needed to develop the discoveries that have already been made. Most discoveries are developed via existing infrastructure.
Increased knowledge, better cooperation between players, data sharing and new technology provide a basis for new discoveries, quicker development and improved recovery in future years. This will be dependent on a continued willingness and ability to invest among licensees on the NCS.
In December, the Norwegian Offshore Directorate published the report "An evolving player landscape". This study presents new company categories and development trends for activity and resource growth distributed across these new company categories. The report is the first phase of a larger study. Further efforts will be presented in a new resource report we are planning to publish in 2026.
It has been a good exploration year
This has been the best exploration year on the NCS in ten years, with the exception of 2021. Many discoveries were made, some of which were significant. In volume (oil equivalent), these discoveries amount to the best resource growth in several years. A number of these discoveries are the result of utilising new and advanced technology.
49 exploration wells were terminated, 40 of which were wildcat wells, and 21 new discoveries were made. The preliminary overall estimate for these discoveries is 67 million standard cubic metres of recoverable oil equivalent (424 million barrels of o.e.). This amounts to a resource growth that is higher than the previous year. More than twice as much liquid was discovered, as compared with gas.
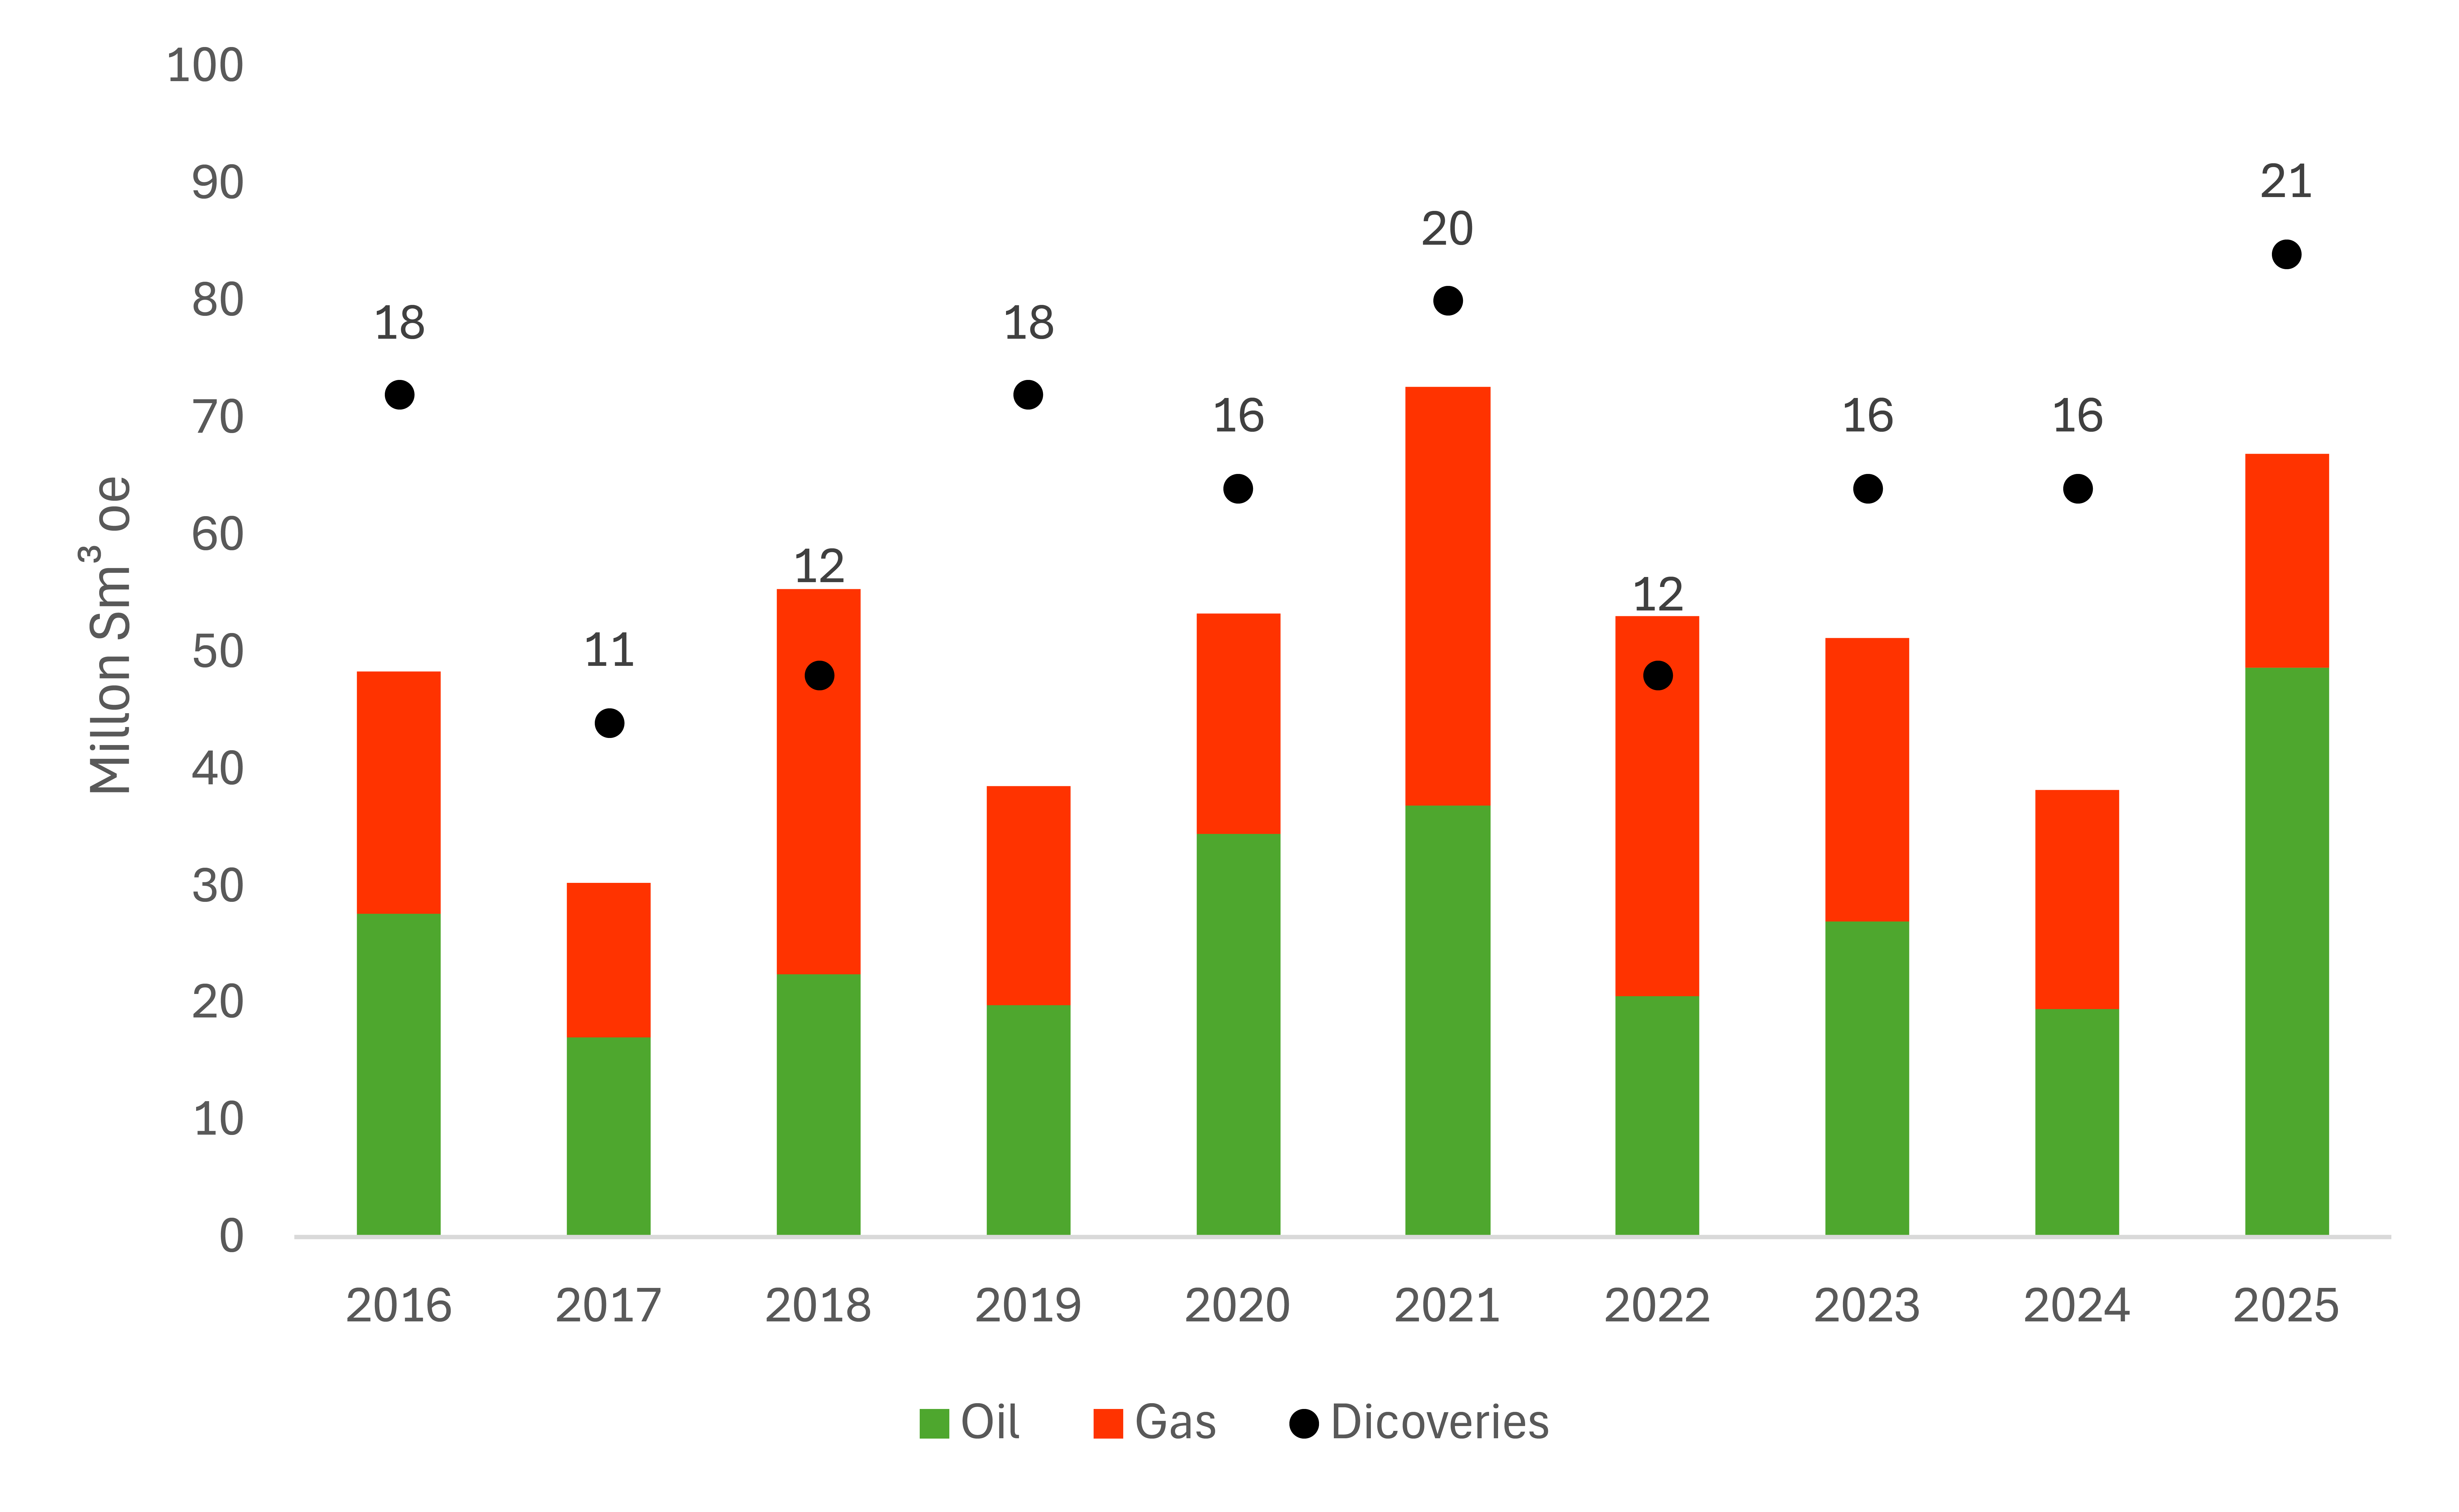
Discovery volumes between 2016 and 2025.
The largest discoveries in 2025:
- The Omega Alfa exploration campaign: oil discovery in four wellbores in the area around Yggdrasil in the North Sea.
- The Lofn/Langemann prospect: two gas/condensate discoveries in the North Sea.
- The Kjøttkake prospect: Oil and gas discovery in the North Sea.
2025 was also marked by technological milestones. Two very long wellbores were drilled:
Aker BP set a new record in the Omega Alfa exploration campaign in the Yggdrasil area. This is the longest exploration wellbore (24/1-14 C) ever drilled on the NCS, measuring 10.7 kilometres.
OKEA drilled the Talisker (31/4-A-15 B) exploration well on the Brage field in the North Sea with a measured length of 10.2 kilometres. This is one of the longest exploration wells on the NCS.
These record-long exploration wells show how advanced drilling technology provides increased flexibility in exploration, and the opportunity to test multiple targets in a single well.
This figure shows exploration results for 2025. (These are the volumes reported in press releases over the course of the year). *The estimated resources are the overall result of four discoveries in the Omega Alfa exploration campaign.
The map under shows where the discoveries were made on the shelf. Update 3 July 2026: The figure for Tallisker is incorrect. The correct range is 2.4–5.21 MSm³ oe, with an average of 3.9 MSm³ oe.
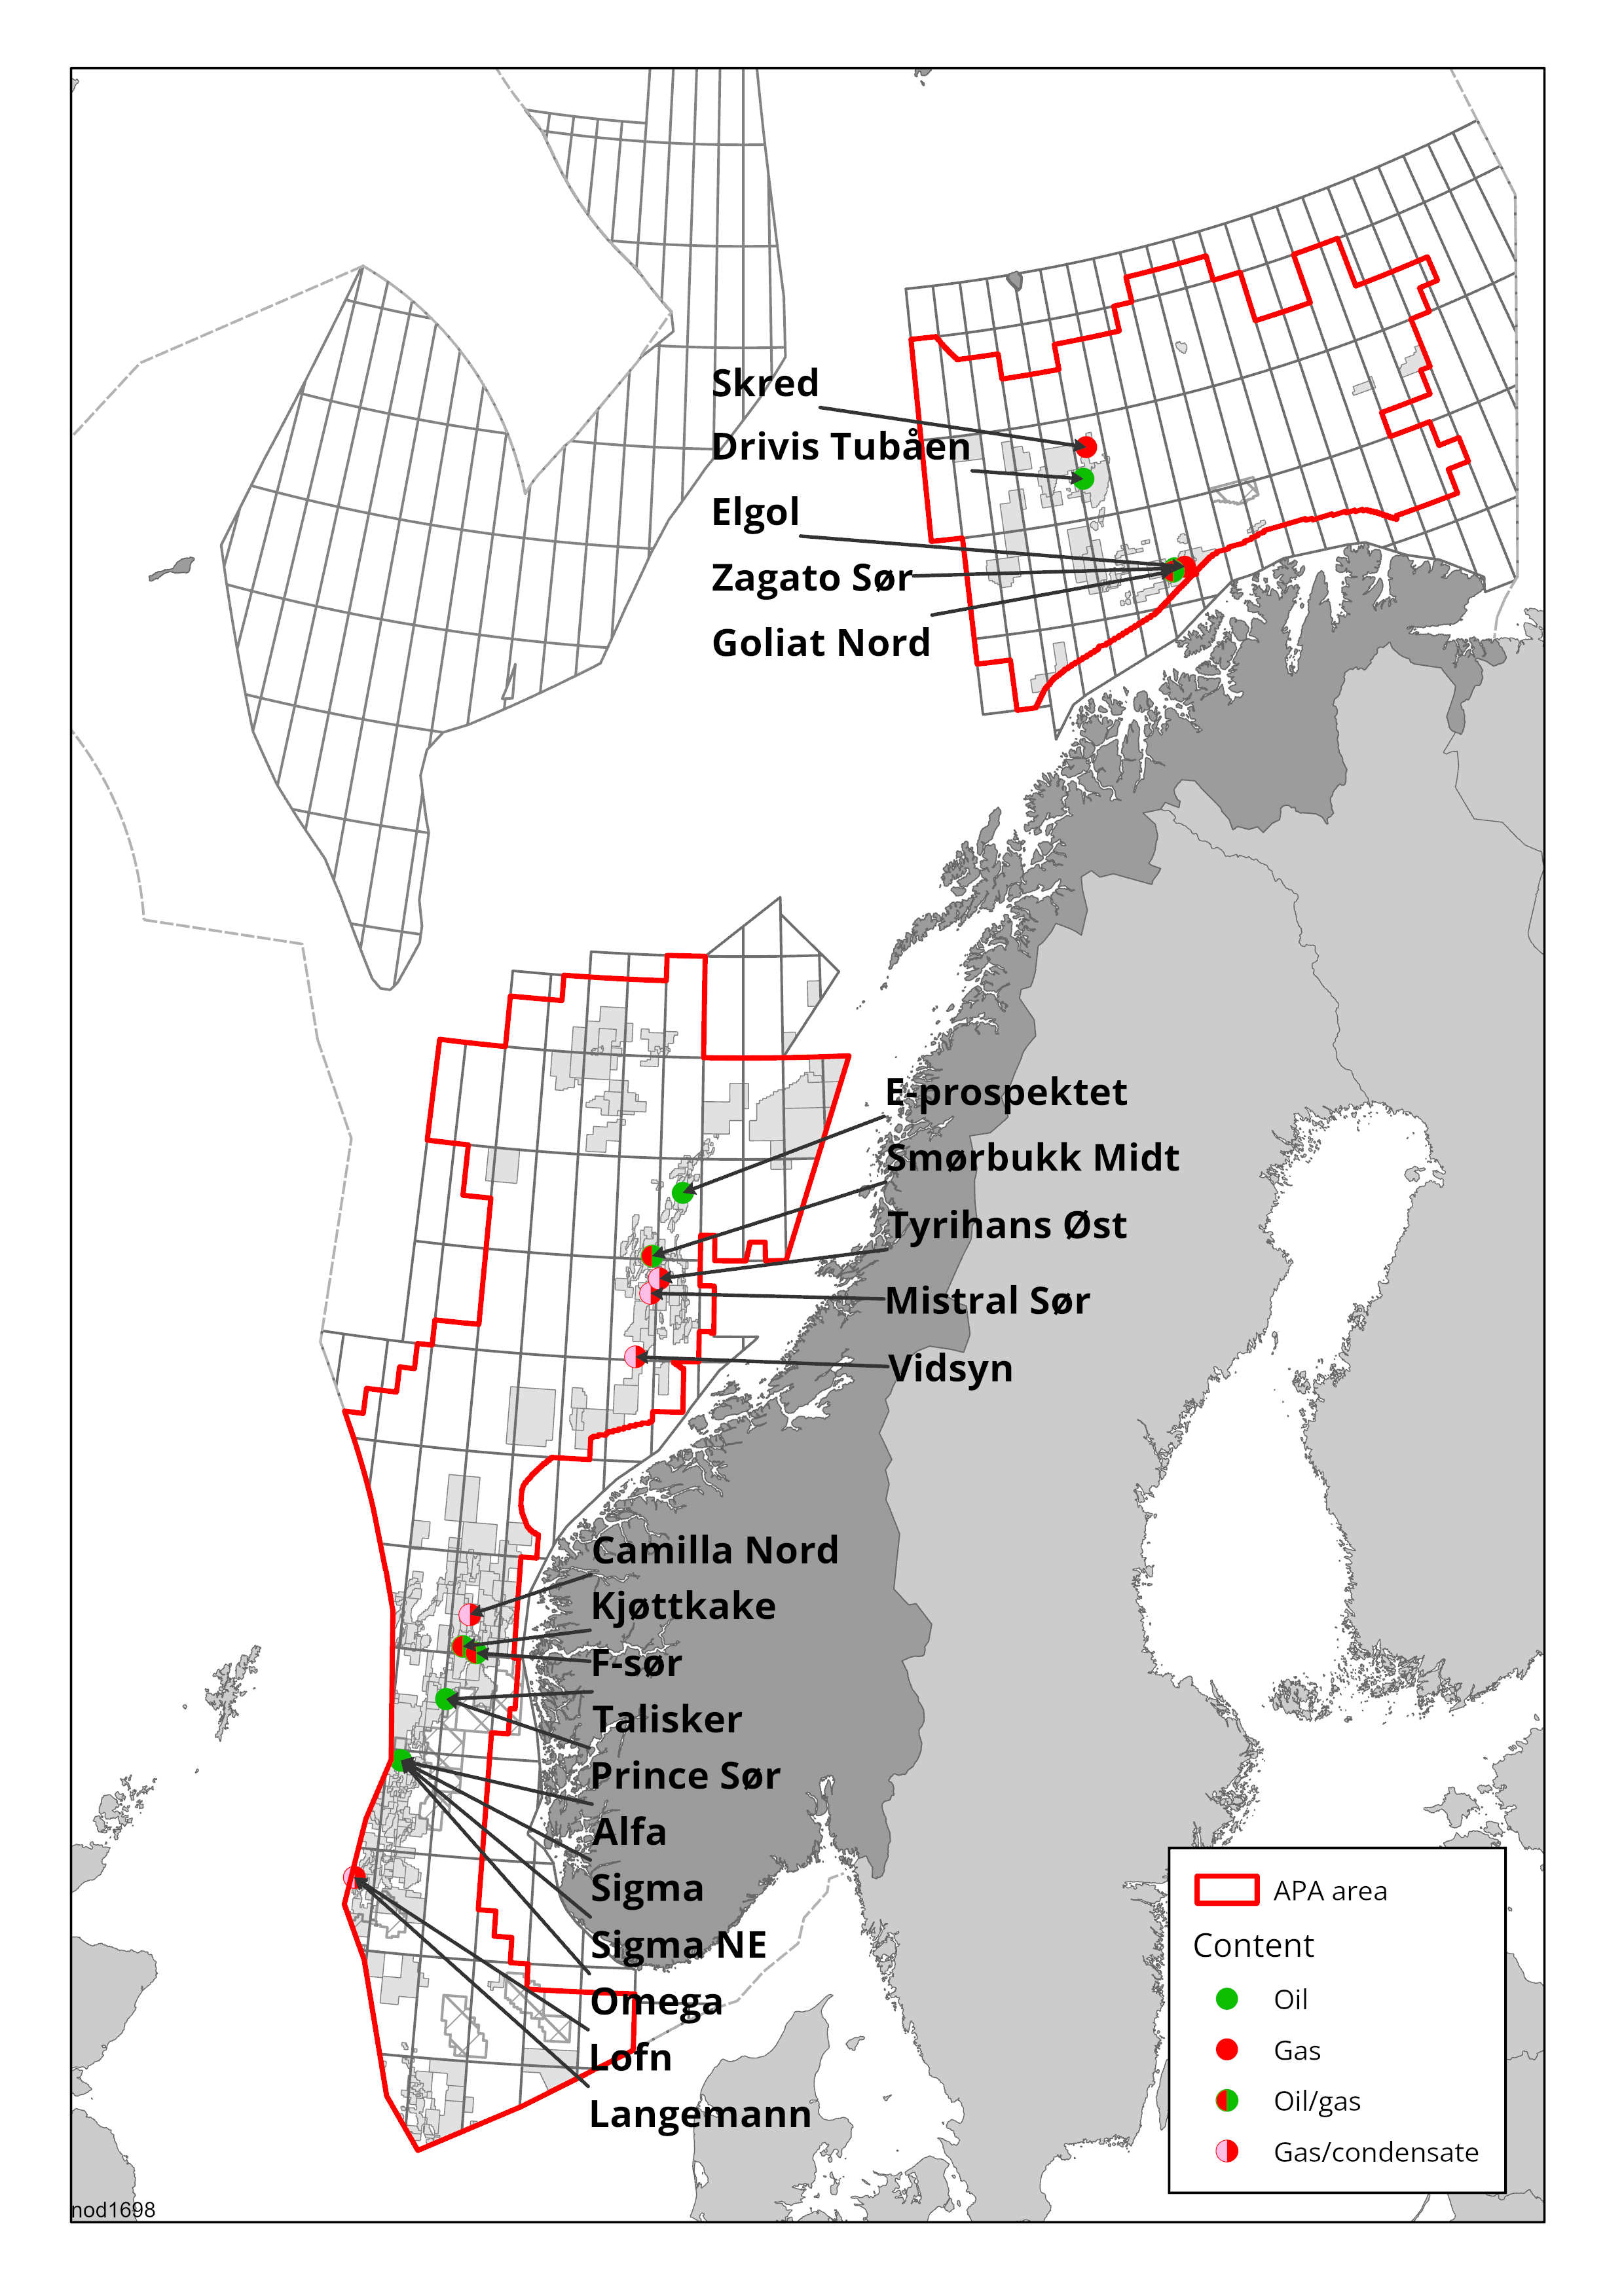
In 2026, the Norwegian Offshore Directorate expects a total of about 40 exploration wells, where 28–32 will be in the North Sea, 4–6 in the Norwegian Sea and 4–6 in the Barents Sea.
At the end of 2025, there were 91 discoveries still awaiting a potential development decision. They comprise certain larger discoveries and several minor ones in all ocean areas on the shelf. The North Sea has the most discoveries.
This table shows a summary of discoveries made in 2025. (These are the volumes reported in press releases over the course of the year. *The estimated resources are the overall result of four discoveries in the Omega Alfa exploration campaign.
| Ocean area | Prospect name | Wellbore | Production licence | Operator | Content | Size, million Sm3 oe |
| North Sea | Langemann | 15/5-8 A | 1140 | Equinor | Gas and condensate | 1-8 |
| North Sea | Lofn | 15/5-8 S | 1140 | Equinor | Gas and condensate | 3,5-10 |
| North Sea | Omega | 25/1-14 | 1249 | Aker BP | Oil | 15,3-21,3* |
| North Sea | Alfa | 25/1-14 A | 1249 | Aker BP | Oil | 15,3-21,3* |
| North Sea | Sigma NE | 25/1-14 C | 1249 | Aker BP | Oil | 15,3-21,3* |
| North Sea | Sigma | 25/1-14 G | 1249 | Aker BP | Oil | 15,3-21,3* |
| North Sea | Talisker | 31/4-A-15 B | 055 | OKEA | Oil | 2,5-5,21 |
| North Sea | Prince Sør | 31/4-A-23 G | 055 | OKEA | Oil | 0,05-0,44 |
| North Sea | Camilla Nord | 35/8-8 S | 248 LS | Harbour Energy | Gas and condensate | 0,4-0,8 |
| North Sea | Kjøttkake | 35/10-15 S | 1182 | DNO | Oil and gas | 6,1-11,8 |
| North Sea | F-sør | 35/11-31 S | 090 | Equinor | Oil and gas | 0,1-1,1 |
| Norwegian Sea | Mistral Sør | 6406/6-7 S | 1119 | Equinor | Gas and condensate | 3-7 |
| Norwegian Sea | Vidsyn | 6406/11-2 S | 586 | Vår Energi | Gas and condensate | 4-6,4 |
| Norwegian Sea | Tyrihans Øst | 6407/1-B-2 H | 1121 | Equinor | Oil and gas condensate | 0,2-1,3 |
| Norwegian Sea | Smørbukk Midt | 6506/12-PB-3 H | 094 | Equinor | Oil and gas condensate | 1-3 |
| Norwegian Sea | E-prospektet | 6507/5-13 S | 212 | Aker BP | Oil | 0,64-1,43 |
| Barent Sea | Goliat Nord | 7122/7-8 | 229 | Vår Energi | Oil and gas | 0,4-0,8 |
| Barent Sea | Zagato Sør | 7122/8-3 S | 229 | Vår Energi | Oil | 2,4-6,8 |
| Barent Sea | Elgol | 7122/9-2 | 1131 | Vår Energi | Gas | 0,4-3 |
| Barent Sea | Skred | 7220/5-4 | 532 | Equinor | Gas | 0,3-0,5 |
| Barent Sea | Drivis Tubåen | 7220/7-CD-1 H | 532 | Equinor | Oil | 1,5-2,3 |
New technology for tight reservoirs
Continuous technology development in the oil and gas industry is a necessary contribution towards generating the greatest possible value for society. This is why the Norwegian Offshore Directorate must be a driving force for developing new technology, including digitalisation, throughout the value chain.
Over the last two years, we have had a particular focus on improving recovery in tight reservoirs (Norwegian only) on the NCS.
Effective production of large volumes of oil and gas from tight reservoirs will require both new technology and cost reductions. Such solutions have already been utilised on a large scale in other countries. Close cooperation between the players will be crucial to succeed in implementation on the NCS. This also frequently involves time-critical resources, which must be quickly tied back to existing installations to ensure profitable extraction.
The following is a selection of technologies relevant for tight reservoirs:
Dynamic fracturing: This method involves fracturing the reservoir rock and keeping the fractures open by filling them with sand. This makes it easier for oil and gas to flow into the well, and increases the production potential.
Low-cost drilling: This is a method to drill wells that uses a continuous length of flexible pipe spooled off a drum. The technology is effective in lowering drilling costs and can achieve profitability in smaller deposits.
CAJ technology (Controlled Acid Jetting): Technology developed specifically to increase productivity in long horizontal wells where traditional methods have a limited range.
The Norwegian Offshore Directorate has organised an annual Technology Day over the last four years. This is primarily aimed at licensees on the NCS. The objective is to share experience from implementing new technology, in line with our tec
Download: Background data (Excel)
Data management, digitalisation and cooperation
Read about:
- Digitalised RNB data provide a better basis for decision-making
- New dashboards make it easier to extract data
- Diskos – our national data repository
- Force – 30 years of cooperation
Digitalised RNB data provide a better basis for decision-making
The Norwegian Offshore Directorate is responsible for collecting, storing and providing access to available data from the Norwegian shelf.
Each year, it is our job to collect information about projects and resource volumes, as well as forecasts for production, costs and emissions/discharges from the operators. We quality-assure this data, make our own assessments and create consistent forecasts for production, costs and emissions/discharges. This effort is an important part of the revised national budget (RNB), which is presented in May.
Extensive efforts are under way alongside the industry to establish a reporting solution for RNB data. This will simplify how licensees report, and also provide more accurate data. The data for this year's reporting was received 100 per cent digitally. This solution will be further refined and adapted in 2026.
Moving forward, this will ensure more uniform reporting across the companies, because data reported to the authorities is also shared between licensees in the production licences, and actively used in planning. Shared standards and definitions increase the value of the data, thereby providing a better basis for decision-making.
New dashboards make it easier to extract data
This year, the Norwegian Offshore Directorate developed digital dashboards to make it easier to extract data about the NCS:
Key figures associated with petroleum activities on the NCS were published on sodir.no just before the summer. You can find the interactive dashboards here: Key figures - Norwegian Offshore Directorate
The Norwegian Offshore Directorate's dashboard with easy access to statistics for exploration wells and technical discovery rates can be found here: Exploration well statistics - Norwegian Offshore Directorate
This autumn, the Directorate launched a dashboard with an overview of the licensees' petroleum resources and reserves on the NCS. The dashboard can be found here.
In addition to information about the petroleum industry, a new interactive map of deep sea data was launched. It provides an overview of mapping and sampling carried out in the deep sea on the NCS. Open the Deep Sea Surveys map
The new dashboards can help provide greater transparency and better understanding of the activities on the NCS. They also represent crucial steps in the direction of more data-driven public administration.
The data are also available on the Directorate's FactPages.
Diskos – our national data repository
2025 marks the 30th anniversary of the creation of Diskos. Diskos is a national data repository for exploration and production-related information from the NCS and a partnership between the authorities and the industry.
This solution has allowed licensees on the NCS to access data when they need it – as opposed to each licensee storing their own data individually. Sharing data has given the NCS a competitive advantage and has been an important contribution toward the resources generating the greatest possible values for society.
The industry is reporting an increasing volume of data to Diskos. Reported data have increased by almost six petabytes; from 16 in 2023 to 22 in 2025.
Force – 30 years of cooperation
2025 is also the 30th anniversary of FORCE (Forum for reservoir characterization, reservoir engineering and exploration technology cooperation), where the Norwegian Offshore Directorate plays a leading role.
All major companies on the NCS are members of FORCE. This forum aims to highlight opportunities for improved recovery as well as serve as a driving force across production licenses.
More information can be found at www.force.org
Download: Background data (Excel)
New industries on the shelf
Read about:
- CO2 storage up and running as an industry on the NCS
- Mapped seabed minerals and deep-sea environments
CO2 storage up and running as an industry on the NCS
2025 saw Northern Lights complete its first successful CO2 injection. This means that the world’s first full-scale value chain for carbon capture and storage is now well under way on the NCS. More than 39,000 tons of CO₂ were injected last year.
The Northern Lights plant in Øygarden is the only plant in the world that can receive CO2 across national borders. The Norwegian authorities have approved development plans for commercial storage of at least 5 million tonnes of CO2 per year. Agreements have been entered into with industrial players both in Norway and abroad.
Three licences were awarded in 2025 pursuant to the Regulations relating to exploitation of subsea reservoirs on the continental shelf for storage of CO₂ and relating to transportation of CO₂ on the continental shelf. Two of these licences were offered in 2024, and awarded in February 2025. There was one licensing round in 2025, with announcement in March and awards in June. One licence has been relinquished to the authorities.
A total of 13 licences have been awarded; one exploitation licence and 12 exploration licences. The potential storage volume in these projects exceeds two billion tonnes, while the potential in these areas is more than 10 billion tonnes. How much of this that actually can be stored will depend on several factors, including information from further mapping, access to CO2 in the market and which development solution the project ultimately chooses.
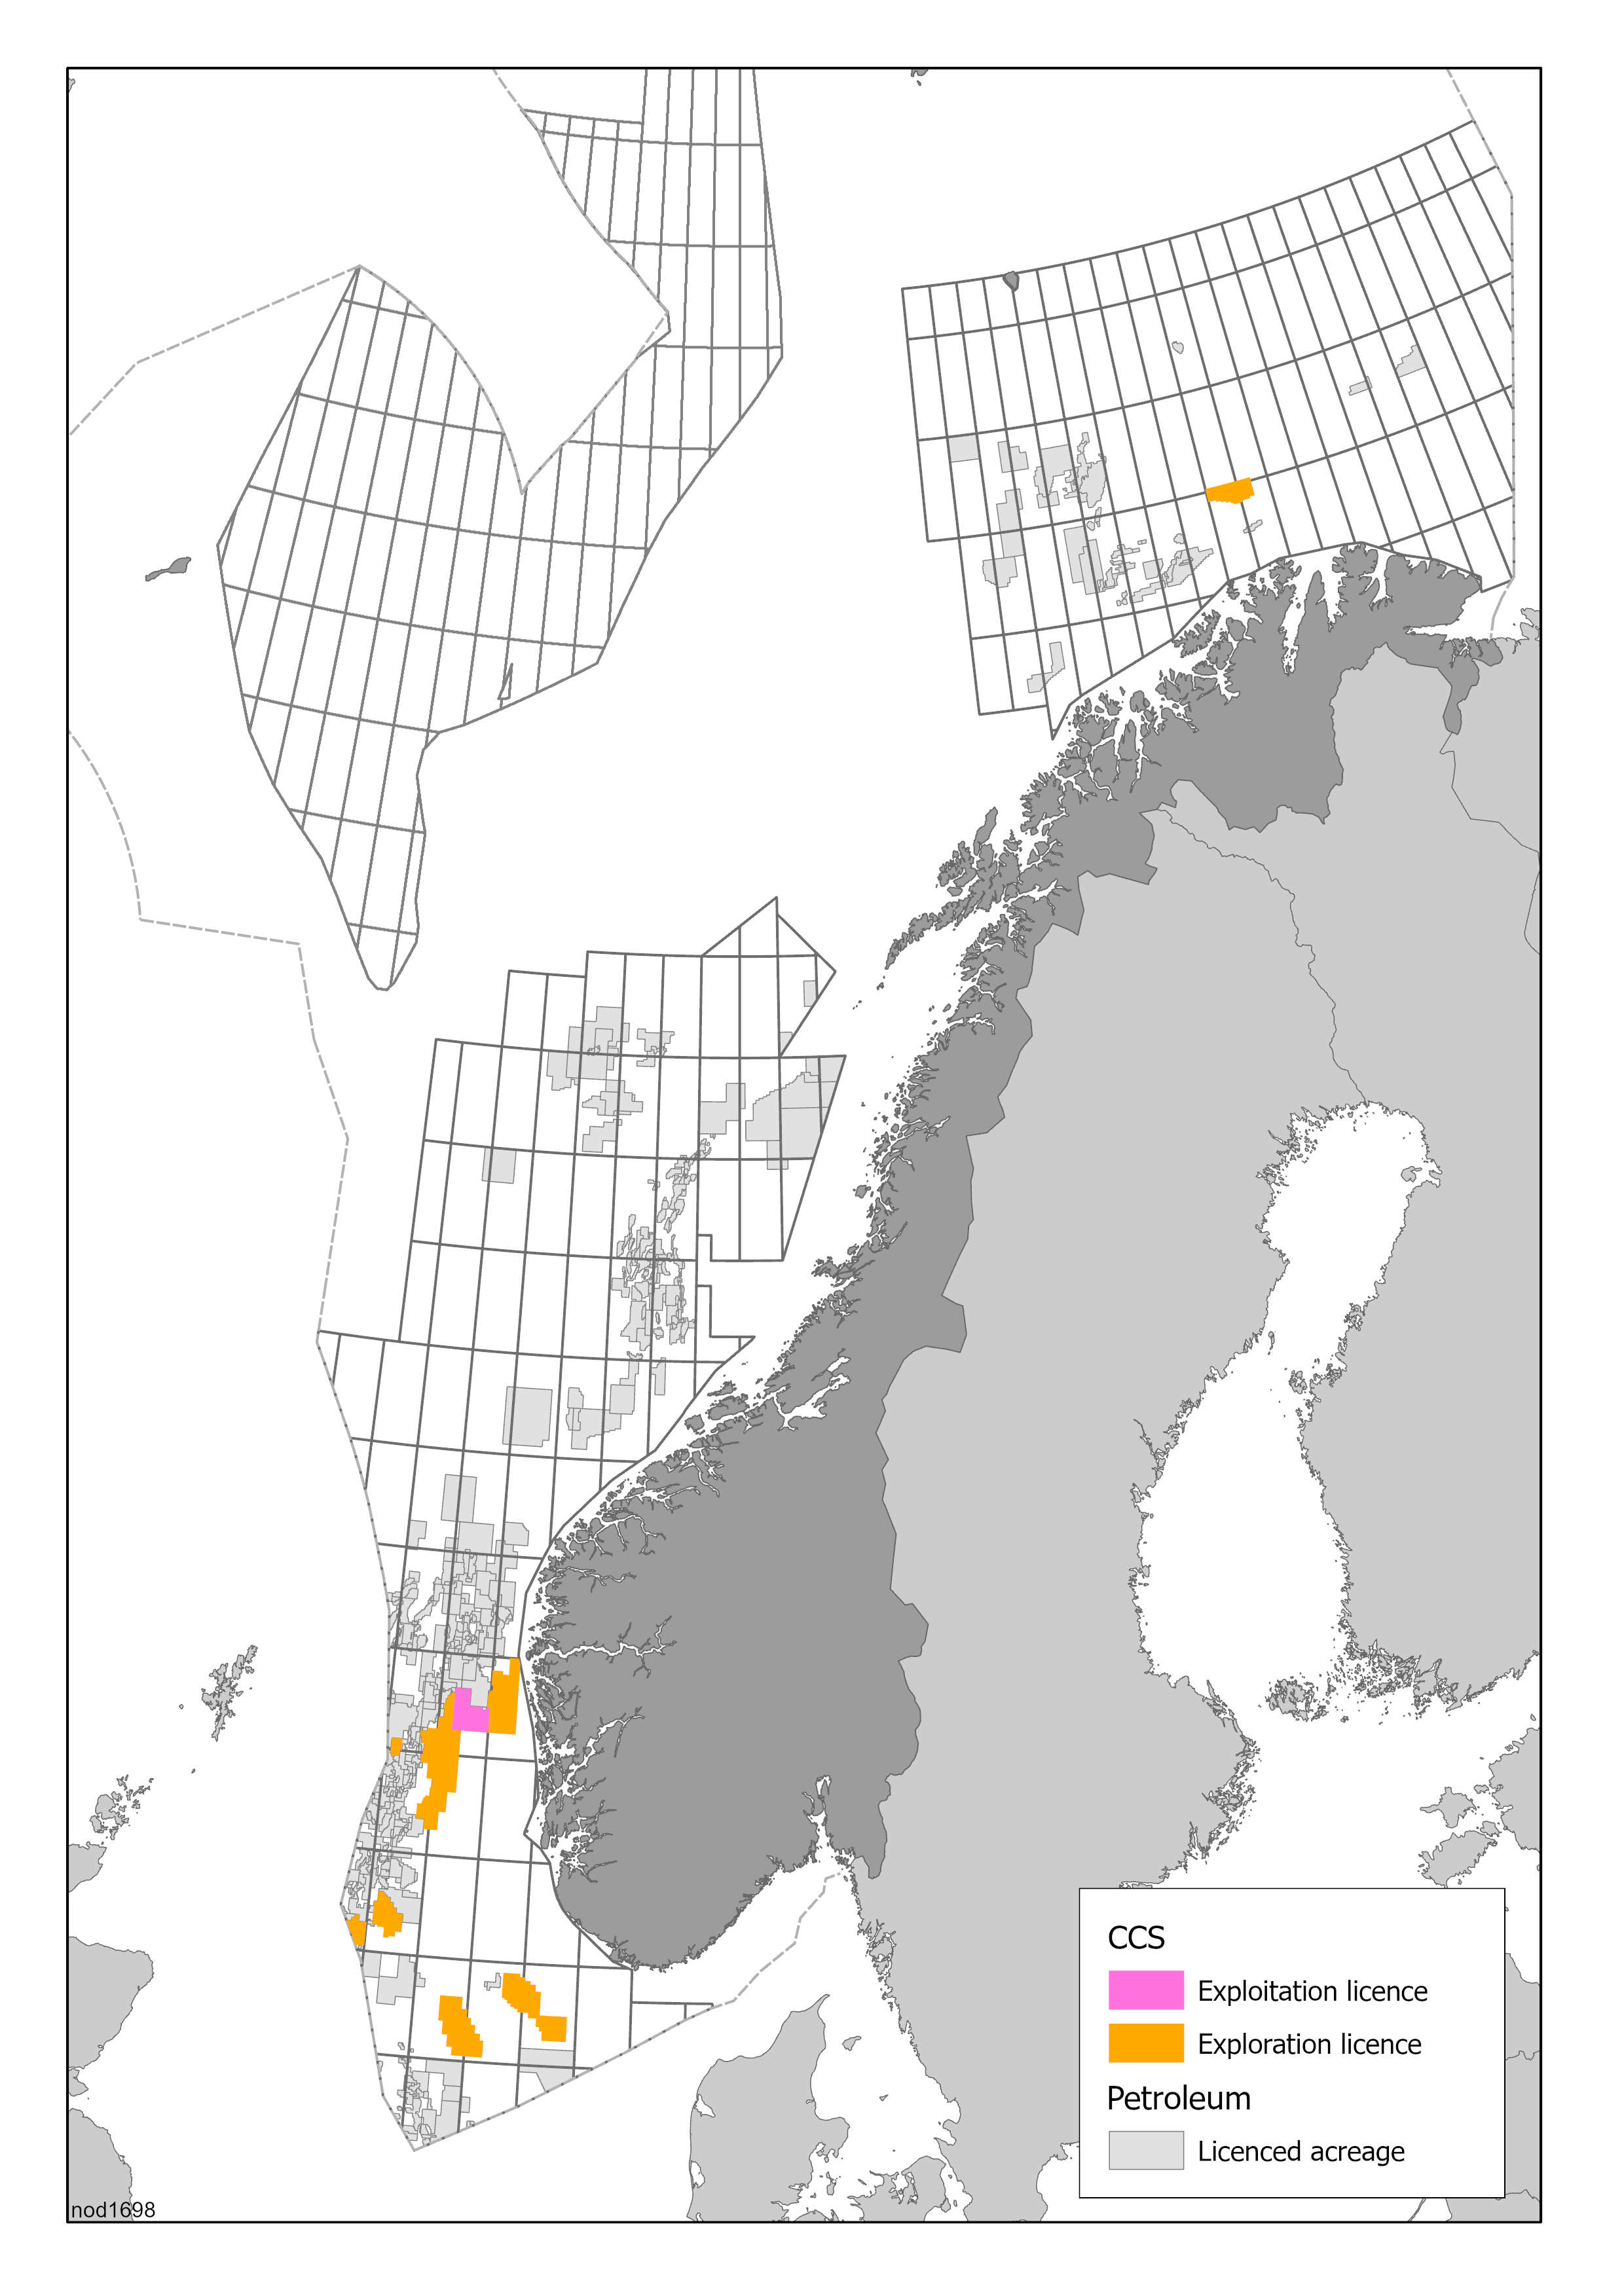
The NCS has a theoretical storage capacity of more than 80 billion tonnes of CO2, the equivalent of about 1800 years of Norway's total CO2 emissions at current levels.
Learn more about CO2 storage and the different types of licences in Resource Report 2024.
Coexistence between CCS and petroleum
Several of the awarded exploration licences for CCS (carbon capture and storage) are located near producing petroleum fields. CO2 injection and petroleum production both affect the pressure in the aquifer. This means that they can impact each other's activity. The Norwegian Offshore Directorate is working on a project to address issues between CO2 storage and petroleum activities. This work is using a large reservoir model that can provide an indication of how the two industries' activities can have an impact on each other.
Mapped seabed minerals and deep-sea environments
In 2025, the Norwegian Offshore Directorate coordinated three research expeditions in the Norwegian Sea and the Greenland Sea and collected large volumes of water depth data (bathymetry), video data and sediment cores.
The objective is to map deposits of seabed minerals and acquire various deep-sea environmental data. One expedition acquired samples for the Mareano programme, where the Norwegian Offshore Directorate is part of both the Programme Group and Executive Group.
Read more about the expeditions here.
Data from expeditions in 2025 has been made available.
The Norwegian Offshore Directorate cooperates closely with the academic community in its deep-sea mapping efforts.
In 2026, the Norwegian Offshore Directorate is planning to conduct a new resource assessment for seabed minerals based on data obtained in recent years.
The Directorate has procured an autonomous deep-sea AUV along with the University of Bergen (UiB). It will be operated by UiB and can be used to map the deep sea.
The Norwegian Offshore Directorate has also purchased a multibeam echo sounder, which is owned by the University of Tromsø (UiT) and installed on the R/V Helmer Hanssen research vessel. This echo sounder provides better image resolution for bathymetric mapping.
In March, the Centre for Deep Sea Research at UiB and the Norwegian Offshore Directorate found a new sulphide deposit on the NCS.
Download: Background data (Excel)